
Key Takeaways
- All risk shipping insurance covers physical loss or damage from any external cause, unless specifically excluded, offering broader protection than restrictive named peril policies.
- Carrier liability is a legal cap, often limiting payouts to $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared.
- Evaluating all risk vs named peril reveals that true shipper’s interest coverage removes the need to prove carrier negligence during the claims process.
- Shared exclusions like mechanical and electrical derangement, insufficient packing, and inherent vice apply to standard cargo insurance, ShipSimple’s included, unless caused by an insured peril.
- ShipSimple provides automated coverage backed by CNA Canada, offering limits up to $250,000 for parcel and $500,000 for freight with transparent online quotes.
All risk shipping insurance is a comprehensive policy that covers physical loss or damage from any external cause during transit, unless the specific cause is explicitly excluded. For businesses moving high-value goods across Canada and internationally, understanding the critical differences between all risk vs named peril coverage is essential for protecting capital and stabilizing profit margins. Relying on default carrier programs often leaves shippers exposed to devastating financial losses when inevitable transit disasters occur.
Fact Block
- Carrier limits default to $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared.
- According to Verisk CargoNet, cargo theft incidents in North America surged by 59% in the third quarter of 2023 compared to the previous year. (Source: Verisk CargoNet)
- ShipSimple’s all risk shipping insurance provides limits up to $250,000 for parcel and $500,000 for freight.
- Statistics Canada reports that retail e-commerce sales reached $3.8 billion in December 2023, highlighting the massive volume of goods moving through domestic parcel networks. (Source: Statistics Canada)
1. Understand the True Financial Risk of Shipping Valuable Goods
To understand the true financial risk of shipping valuable goods, businesses must recognize the massive gap between an item’s replacement cost and a carrier’s weight-based payout. Relying solely on default carrier limits exposes shippers to catastrophic capital depletion if a high-value asset is lost, stolen, or destroyed in transit. Securing all risk shipping insurance mitigates this exposure by protecting the actual declared value of your inventory.
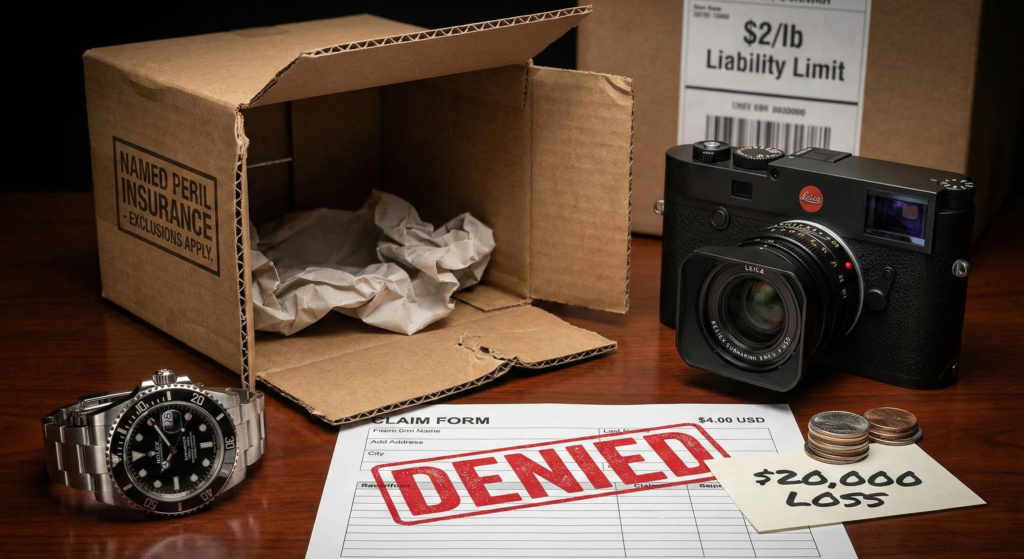
For businesses and private sellers in the Canadian market, moving a $20,000 luxury watch or a $50,000 medical device through standard channels is a high-stakes operation. Modern sorting hubs are high-speed, automated environments where packages are subjected to kinetic shocks, mechanical drops, and intense vibration. These are daily operational realities that standard carrier liability frequently excludes or caps at nominal amounts. Without a dedicated risk mitigation strategy, shippers are essentially self-insuring their most valuable assets against theft, damage, and mysterious disappearance.
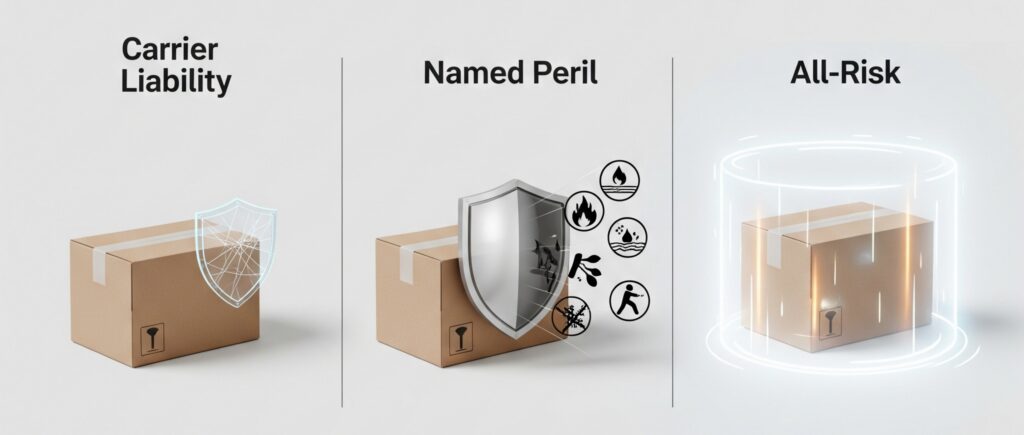
Navigating this landscape safely requires a clear understanding of the distinct tiers of protection available in the logistics world. Many shippers mistakenly believe that the default coverage included with their shipping label is sufficient. However, this basic protection is designed to limit the carrier’s financial exposure, not to make the shipper whole after a loss. To protect your balance sheet, you must evaluate the differences between carrier liability, named peril contracts, and comprehensive shipper’s interest policies.
What is the difference between carrier liability and true insurance?
The difference between carrier liability and true insurance is that liability is a legal cap protecting the carrier, whereas insurance is a dedicated policy protecting your financial interest. Carrier liability requires you to prove carrier negligence, while true insurance indemnifies you based on the declared value of the goods.
Carrier liability is the default protection included with your shipping label. It is not insurance. Instead, it is a contractual limitation of liability that dictates the maximum amount a carrier will pay if they are found at fault for a loss. For freight shipments, this limit is typically $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared. For parcel shipments with couriers like Canada Post, FedEx, UPS, DHL, or Purolator, the default limit is often capped at a flat $100.
True all risk shipping insurance operates on an entirely different framework. It is a separate contract between the shipper and an insurance provider, designed to indemnify the shipper up to the declared value of the goods. When you purchase a dedicated policy, you are no longer bound by the carrier’s weight-based limits or their internal negligence investigations. This separation of logistics execution from financial protection is a fundamental best practice for any business shipping high-value inventory.
2. Evaluate the Limitations of Named Peril Coverage
Evaluating the limitations of named peril coverage reveals that these policies only compensate shippers if the loss results from a specific event explicitly listed in the contract. If the cause of damage is not on that narrow list, the claim is denied, leaving the shipper entirely responsible for the financial loss. This restrictive framework makes named peril unsuitable for complex modern supply chains.
Named peril insurance, often known as specified perils coverage, is a step above basic carrier liability but still falls short of comprehensive protection. These policies typically list specific catastrophic events, such as fire, lightning, sinking, or vehicle collision. While these events certainly happen, they represent only a fraction of the actual risks goods face during transit. The most common causes of loss in modern logistics include mysterious disappearance, theft from unattended vehicles, and impact damage during automated sorting.
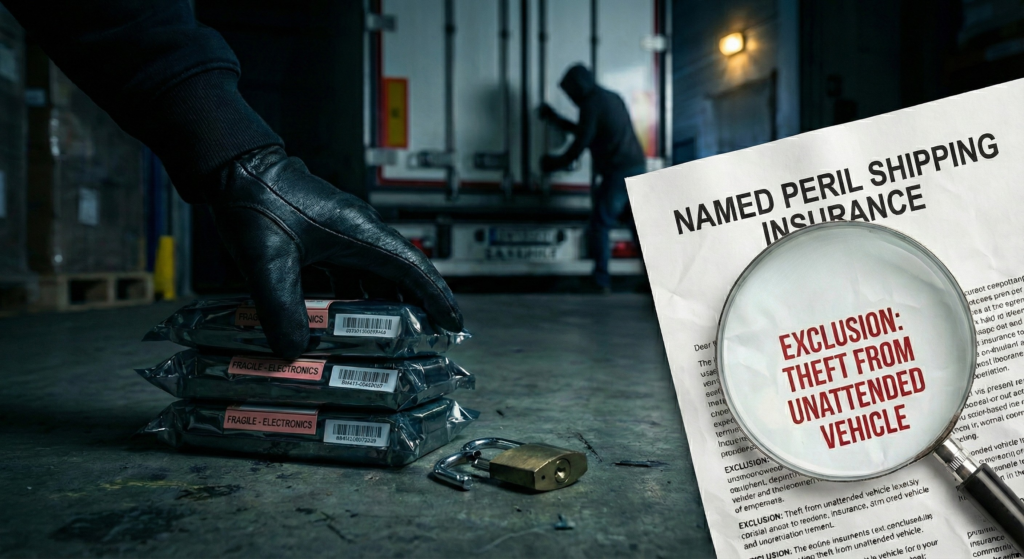
Because named peril policies require the loss to match a listed event exactly, they create significant coverage gaps. If a package is stolen from a porch or lost within a massive distribution hub, a named peril policy will likely deny the claim because “theft” or “mysterious disappearance” is frequently omitted from the list of covered events. For businesses shipping easily liquidated assets like electronics, jewelry, or automotive parts, relying on a named peril contract is a dangerous strategy that can lead to severe financial consequences.
What does named peril coverage mean for Canadian shippers?
For Canadian shippers, named peril coverage means accepting a restrictive insurance contract that requires you to provide concrete evidence that a listed event directly caused the damage to your shipment. You must match the specific circumstances of your loss to the narrow definitions outlined in the policy wording.
This requirement creates a significant administrative hurdle during the claims process. If a pallet of sensitive cinematography equipment arrives with severe impact damage, but the carrier has no record of a vehicle collision or overturn, a named peril policy will not respond. The shipper is left trying to prove exactly what happened inside a closed logistics network, which is nearly impossible without specialized tracking equipment. This dynamic makes named peril coverage a poor fit for high-value, fragile, or theft-attractive commodities.
Why do standard carrier liability programs fail to protect high-value profits?
Standard carrier liability programs fail to protect high-value profits because they cap payouts by weight rather than the actual invoice product cost. A lightweight, high-value item like a luxury watch will only yield a nominal payout, effectively destroying your profit margin on that specific sale.
Consider a scenario where a business ships a $15,000 specialized medical component weighing only 10 pounds. If that shipment is destroyed in a hub sorting accident and the shipper relies solely on carrier liability, the maximum payout under the $2 per pound rule would be a mere $20. The business absorbs a $14,980 loss. This cents-per-pound trap is the primary reason why professional sellers and commercial shippers must secure independent all risk shipping insurance to protect their bottom line.
3. Compare All Risk vs Named Peril in Real-World Scenarios
Comparing all risk vs named peril in real-world scenarios demonstrates that all risk shipping insurance offers significantly broader protection by changing what you need to show during a claim. While named peril requires you to prove the exact cause of loss matches a listed event, all risk allows you to collect on proof of physical loss or damage. This fundamental difference streamlines the recovery process for high-value shipments.
To fully grasp the operational impact of these different protection tiers, shippers must look beyond the policy definitions and examine how they perform when a disaster actually occurs. The logistics environment is unpredictable, and the true value of a risk mitigation strategy is tested during the claims process. The following strategic snapshot illustrates how basic liability, named peril, and comprehensive all risk shipping insurance respond to common transit failures.
Strategic Snapshot: Coverage Comparison
| Feature | Carrier Liability | Named Peril Insurance | ShipSimple All Risk |
|---|---|---|---|
| Valuation | Weight-based cap | Specified in contract | Invoice product cost, or CIF + 10% recommended, elected when you book |
| What You Need to Claim | Proof the carrier was negligent | Proof the specific listed peril occurred | Photos and a description of the damage (for freight, plus a repair estimate or third-party confirmation), or tracking showing non-delivery once the carrier’s waiting period has passed, with no need to prove carrier negligence |
| Claim Time | Can take months | Varies by provider | Under 30 days for approved submissions |
| Shared Exclusions | Excluded | Excluded | Excluded unless caused by an insured peril |
What documentation is required for All Risk vs Named Peril claims?
The documentation required for all risk vs named peril claims differs significantly based on the policy structure. Under named peril, the shipper must provide evidence that a specific listed event occurred; under all risk shipping insurance, you collect on proof of physical loss or damage, along with standard commercial documents like the invoice and tracking record.
When filing shipping insurance claims under an all risk policy, the process is designed to be straightforward. For parcel shipments, you typically need clear photos of all sides of the exterior packaging, photos of the internal cushioning, photos of the damaged item itself, and a description of the damage. For freight shipments, you must also provide a repair estimate or independent third-party confirmation of the damage. In cases of non-delivery, the claim can proceed once the carrier’s waiting period has passed, using tracking that shows non-delivery. There is no need to prove carrier negligence, which drastically reduces the time and friction involved in recovering your capital.
4. Identify the Common Exclusions in All Risk Shipping Insurance
Identifying the common exclusions in all risk shipping insurance is critical because no policy covers every conceivable scenario without limitations. Standard exclusions include delay, inherent vice, insufficient packing, willful misconduct of the insured, and ordinary wear and tear, which are never covered under these policies. Understanding these boundaries ensures you engineer uninsurable risks out of your logistics strategy.
While all risk shipping insurance is the broadest form of coverage available, it is not a maintenance contract or a safeguard against poor preparation. The policy is designed to cover fortuitous, external transit events, not inevitable deterioration or damage resulting from shipper negligence. For example, inherent vice refers to a property of the item itself that causes it to deteriorate without an external event, such as a battery leaking or perishable goods spoiling due to their natural lifespan. These inherent risks are uninsurable.
Similarly, damage resulting from insufficient packing is absolutely excluded. If you ship a fragile antique without proper void fill, or if you load heavy industrial machinery onto a flatbed without adequate blocking and bracing, any resulting damage is considered the fault of the shipper. Professional crating and secure loading are underwriting requirements, not optional suggestions. For specific high-value classes, such as jewelry, watches, and fine art, the policy includes a strict “Warranted Professionally Packed” condition. Breaching this warranty gives the insurer grounds to deny the claim entirely.
How do shared exclusions impact shipping insurance claims?
Shared exclusions impact shipping insurance claims by denying coverage for specific types of damage, such as mechanical and electrical derangement, unless caused by an insured peril. Both standard cargo markets and ShipSimple exclude rust, oxidization, discolouration, scratching, denting, marring, chipping, and insufficient packing, meaning shippers must engineer these risks out of their transit strategy.
When evaluating all risk vs named peril, it is vital to understand that certain risks are universally excluded across the standard cargo market. For example, internal electronic or mechanical failure without external evidence of package damage is excluded under standard cargo insurance too, ShipSimple’s included, unless an insured peril caused it. If a sensitive medical laser or a piece of industrial machinery arrives intact but will not turn on, this mechanical and electrical derangement is not covered unless you can show it was caused by a collision, overturn, or dropped container.
Likewise, ordinary road or rail vibration is not an insured peril. If a load shifts and sustains damage due to poor blocking and bracing, that is considered insufficient packing and is excluded. Shippers must use shock isolation mounts, impact loggers, and professional crating to mitigate these uninsurable risks. All-Risk Shipper’s Interest Insurance changes two things: your goods are valued at CIF + 10% instead of the carrier’s weight-based cap, and you collect on proof of physical loss or damage rather than proof of carrier negligence. It does not broaden the list of covered perils beyond standard cargo market terms.
5. Secure Institutional-Grade Protection for Your Business
Securing institutional-grade protection for your business requires moving away from basic carrier liability and adopting a dedicated all risk shipping insurance strategy. By partnering with a specialized platform, shippers can protect their capital, stabilize their margins, and mitigate the severe financial risks of modern logistics. This proactive approach ensures your balance sheet remains insulated from unpredictable transit disasters.
In the 2026 logistics environment, relying on carrier programs is a high-stakes gamble. The complexity of global supply chains, combined with rising rates of cargo theft and automated handling damage, demands a professional risk-transfer solution. ShipSimple provides an automated all risk overlay backed by CNA Canada, a leading commercial underwriter. This institutional backing ensures that when a catastrophic loss occurs, your claim is handled by a well-capitalized partner dedicated to indemnifying your business, rather than a carrier looking to minimize their liability.
ShipSimple provides shipping insurance only, meaning it does not move parcels. The carrier moves the box; ShipSimple protects the value inside. This clear boundary allows shippers to use their preferred couriers, such as Canada Post, FedEx, UPS, DHL, or Purolator for parcels, and CN Rail or CPKC for freight, while maintaining consistent, high-level financial protection across all shipments. For businesses moving heavy equipment or intermodal containers, ShipSimple’s sister company, RailGateway, provides specialized B2B intermodal rail freight services across Canada, complementing the insurance offering with expert logistics execution.
Why is all risk shipping insurance the best choice for high-value goods?
All risk shipping insurance is the best choice for high-value goods because it values shipments at their declared invoice product cost, or CIF + 10% when elected at booking, rather than a weight-based limit. This means that if a catastrophic loss occurs, the shipper is indemnified based on the Invoice product cost, or CIF + 10% recommended, elected when you book.
When you ship a $100,000 vintage timepiece or a critical aerospace component, the settlement basis is the most important factor in your risk strategy. Standard carrier liability will only pay a fraction of the item’s worth. With a dedicated all risk policy, you declare the true value upfront. If the item is destroyed or lost, the policy settles based on that declared value, up to the policy limits. ShipSimple offers substantial limits of $250,000 for parcel shipments and $500,000 for freight shipments, with higher limits available per-customer upon review.
It is important to note that this is an indemnity policy, not a replacement cost contract. It puts the shipper back in the financial position they were in prior to the loss, up to the declared value. A damaged shipment is assessed and settles as either the cost to repair or, where repair is uneconomic against the sum insured, as a total loss at the declared value. This structure provides predictable, reliable financial recovery without the adversarial negligence investigations required by carrier liability programs.
How does ShipSimple’s automated all risk protection work?
ShipSimple’s automated all risk protection works through a simple three-step online workflow: Product Details, Shipment Details, and Address Details. The platform provides an instant, transparent online quote, allowing shippers to bind coverage in seconds.
This streamlined process democratizes access to institutional-grade protection. Whether you are a private watch collector shipping a single Rolex or a commercial distributor moving daily freight, the workflow is identical. You enter the required information, select your valuation basis (invoice product cost, or CIF + 10% recommended, elected when you book), and secure the coverage. The policy attaches warehouse to warehouse, meaning coverage applies from the moment the goods leave the origin premises until final delivery, including the risk of loading and unloading, provided it is declared as such and there are no country restrictions.
Different commodities carry specific deductibles based on their inherent risk profile. For example, parcel shipments generally have a nil deductible. However, freight shipments are subject to a strict schedule. Electronics, watches, and fragile goods carry a deductible of 3% of the total insured value, minimum $500. Industrial machinery, which is covered for freight but excluded for parcel, carries a deductible of 1% of the total insured value, minimum $500. Industrial machinery must be containerized to bind automatically, and used equipment is subject to a Used Machinery Clause (shippers should ask what this means for their shipment). By understanding these parameters and using the automated platform, shippers can confidently bind coverage in under a minute through the three-step web form for every transit.
Don’t let your hard-earned profits be destroyed by the pennies-on-the-pound liability trap. Treat your logistics with the same professional rigor as your product development and customer service. Secure your shipments, protect your capital, and scale your business with the confidence that only institutional-grade, all risk shipping insurance can provide.
- Get an Instant Shipping Insurance Quote Now
- Learn More About Our All-Risk Damage, Loss, & Theft Coverage
- Contact Our Experts to Secure Your 2026 Shipments
Additional Resources
- Learn More About ShipSimple’s All-Risk Shipping Insurance
- ShipSimple’s Freight & Marine Cargo Shipping Insurance
- ShipSimple’s Parcel Shipping Insurance
- More Helpful Blogs
Frequently Asked Questions
What is the main difference between all risk vs named peril coverage?
The main difference in all risk vs named peril coverage is scope. Named peril only covers explicitly listed events. All risk shipping insurance covers physical loss or damage from any external cause, unless the specific cause is explicitly excluded in the policy.
Does carrier liability provide the same protection as all risk shipping insurance?
No, carrier liability is not insurance. It is a legal cap that defaults to $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared. True all risk shipping insurance protects your actual declared financial value.
Are mechanical failures covered under all risk shipping insurance?
Internal electronic or mechanical failure without external evidence of package damage is excluded under standard cargo policies, ShipSimple’s included. This mechanical and electrical derangement is excluded unless caused by an insured peril, such as a vehicle collision or overturn.
How do shipping insurance claims work for missing packages?
For missing packages, shipping insurance claims can proceed once the carrier’s waiting period has passed. You must provide tracking that shows non-delivery. There is no need to prove carrier negligence when you have a dedicated shipper’s interest policy in place.
What valuation is used for all risk shipping insurance?
The default valuation for all risk shipping insurance is the declared invoice product cost. Shippers can also choose to insure their goods on a CIF + 10% basis, which must be elected when you book the coverage online.