Key Takeaways
- All risk shipping insurance values your goods at their invoice product cost or a declared CIF plus 10 percent, replacing restrictive weight-based carrier liability caps.
- Shippers collect on proof of physical loss or damage rather than proof of carrier negligence, resolving approved claims in under 30 days.
- The ShipSimple platform provides automated coverage limits up to $250,000 for parcel shipments and $500,000 for freight shipments.
- Standard cargo market exclusions apply, meaning mechanical derangement and scratching are excluded unless caused by an insured peril.
- Coverage attaches from warehouse to warehouse, protecting the financial value of the goods while the carrier handles the physical transportation.
All risk shipping insurance is a comprehensive policy that covers physical loss or damage to goods in transit from external causes, subject to specific standard market exclusions. Supply chain volatility exposes Canadian businesses to severe financial losses when shipments are damaged, destroyed, or stolen in transit. Relying on standard carrier liability leaves companies vulnerable to weight-based payout caps that rarely cover the invoice product cost of the goods. Implementing a robust all risk shipping insurance strategy mitigates this exposure, stabilizes profit margins, and means that a single catastrophic transit event does not derail quarterly revenue goals.
The Financial Reality of Transit Risk
Supply chain volatility exposes Canadian businesses to severe financial losses when shipments are damaged or stolen in transit. Relying on standard carrier liability leaves companies vulnerable to weight-based payout caps that rarely cover the invoice product cost of the goods. Implementing a robust shipping insurance strategy mitigates this exposure and stabilizes profit margins.
The logistics landscape in North America is increasingly complex. Goods moving across the country face multiple touchpoints, cross-docking operations, and thousands of miles of road or rail transit. Every time a pallet is lifted by a forklift or a parcel is sorted on a conveyor belt, the risk of physical impact increases. Standard carriers operate on volume and speed, meaning that despite their best efforts, a certain percentage of cargo will inevitably suffer damage or loss. For businesses shipping high-value inventory, accepting this baseline attrition as a cost of doing business is a dangerous financial strategy.
When a loss occurs, many shippers mistakenly believe the carrier will simply reimburse them for the broken items. This assumption leads to devastating financial surprises. Carriers operate under strict liability limitations designed to protect their own balance sheets, not the shipper’s inventory. Understanding the vast difference between these standard carrier terms and dedicated all risk insurance is the first step in building a resilient logistics operation.
Fact Block: The Scale of Transit Exposure
- Carrier Liability Limits: Standard carrier liability in Canada is capped at $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared.
- Cargo Theft Surges: Verisk CargoNet reported a 59 percent year-over-year increase in cargo theft incidents across the United States and Canada in the third quarter of 2023.
- Freight Volumes: Transport Canada reports that Canadian railways move over 330 million tonnes of freight annually, exposing massive volumes of goods to transit vibration and impact risks.
- Coverage Capacity: The ShipSimple platform provides automated coverage limits up to $250,000 for parcel shipments and $500,000 for freight shipments.
Advantage 1: Valuation Based on Declared Value
The primary advantage of this coverage is that shipments are valued at their invoice product cost rather than a restrictive weight-based metric. Shippers can also elect to insure on a CIF plus 10 percent basis when they book their coverage. This structure helps businesses recover the invoice product cost of their lost inventory.
Standard carrier liability is fundamentally disconnected from the invoice product cost of the goods being shipped. When a carrier accepts a load, their default liability is calculated strictly by the weight of the cargo. In Canada, this limit is typically set at $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared. This metric works adequately for shippers moving heavy, low-value commodities like raw lumber or bulk gravel. However, for companies shipping electronics, precision machinery, or luxury goods, this weight-based calculation creates a massive financial gap.
Consider a company shipping a specialized server rack weighing 50 kilograms but valued at $20,000. If that server is destroyed in a collision, the carrier’s maximum liability payout would be roughly $220. The shipper is left to absorb a $19,780 loss. This scenario plays out daily across the logistics industry, devastating the profit margins of businesses that failed to secure proper shipment protection before the goods left their facility.
Understanding the Cents-Per-Pound Trap
The cents-per-pound trap is the most common pitfall for new shippers. Carriers prominently display their liability coverage in their terms and conditions, leading many businesses to believe they are fully protected. The reality is that this liability is a legal cap designed to limit the carrier’s exposure to catastrophic claims. It is not an insurance policy designed to make the shipper whole. Avoiding this trap requires a proactive shift from relying on carrier terms to securing dedicated shipper’s interest coverage.
Dedicated all risk shipping insurance completely removes weight from the settlement equation. When a business books coverage, they declare the invoice product cost of the goods. The default valuation basis is the invoice product cost. This means that if a total loss occurs due to an insured peril, the settlement is based on the real financial value of the inventory, up to the declared limit. This fundamental shift in valuation is what transforms shipping from a high-stakes gamble into a predictable, managed operational expense.
The Role of CIF Plus 10 Percent
For businesses looking to maximize their financial recovery, the valuation can be further optimized. Shippers have the option to insure their goods on a CIF plus 10 percent basis, which must be elected at the point of booking coverage. CIF stands for Cost, Insurance, and Freight. This valuation method covers the invoice cost of the goods, the cost of the insurance premium itself, and the freight charges paid to move the cargo.
The additional 10 percent is designed to buffer against unseen administrative costs and the general friction of managing a disrupted supply chain. By electing this valuation, businesses ensure that a lost shipment does not result in sunk freight costs or wasted premium expenses. This comprehensive approach to valuation is a cornerstone of effective transit risk mitigation, helping the balance sheet remain protected even when the physical cargo is destroyed.
Advantage 2: Claims Without Proving Carrier Negligence
A dedicated policy allows shippers to collect on proof of physical loss or damage rather than proof of carrier negligence. Businesses simply provide photos and a description of the damage, or tracking showing non-delivery once the carrier’s waiting period has passed. This streamlined approach resolves claims in under 30 days for approved submissions.
The second major flaw in relying on carrier liability is the burden placed on the shipper during the claims process. Carrier liability is fault-based. To secure a payout, the shipper must definitively prove that the carrier was negligent and directly caused the damage. Carriers employ entire departments dedicated to defending against these claims, using a wide array of legal defenses to deny responsibility. They may argue that the packaging was insufficient, that the damage was caused by an act of God, or that the shipper loaded the trailer improperly.
Fighting a carrier negligence defense is a time-consuming and frustrating process. Shippers often spend months exchanging emails, providing endless documentation, and arguing over the exact moment the damage occurred. Even if the shipper successfully proves negligence, the final payout is still subject to the restrictive weight-based caps discussed earlier. This adversarial system drains internal resources and delays the financial recovery necessary to replace the damaged goods.
The Reality of Carrier Negligence Defenses
Carriers protect themselves first. When a claim is filed, their immediate operational goal is to determine if they can legally deny it under their tariff rules. If a shipment arrives with a damaged exterior, the carrier might argue that the internal cushioning was inadequate for the normal rigors of transit. If a shipment is delayed by weather and subsequently damaged, they will cite force majeure. The shipper is forced to act as an investigator, gathering evidence to overcome these built-in defenses.
All risk insurance fundamentally changes this dynamic. The coverage is designed to respond to physical loss or damage from external causes, regardless of whether the carrier was legally at fault. The adversarial relationship is removed. The shipper does not need to prove that the forklift driver was speeding or that the truck driver took a corner too sharply. They only need to prove that the goods were in good condition when they left the origin facility and arrived damaged at the destination.
Required Documentation for Freight Claims
While the need to prove negligence is eliminated, shippers must still provide clear evidence of the loss. The required documentation is straightforward and logical. For a damaged freight shipment, the shipper must provide clear photos of the damaged goods and the packaging, a detailed description of the incident, and a repair estimate or independent third-party confirmation of the damage. The shipper must also retain all packaging and the damaged items until the claim is finalized.
For missing shipments, the process is equally clear. The claim can proceed once the carrier’s waiting period has passed, using tracking that shows non-delivery. By providing this standard documentation, businesses enable the underwriting team to process the settlement quickly. This efficiency is what allows approved submissions to be resolved in under 30 days, a stark contrast to the months-long battles typical of carrier liability disputes.
Advantage 3: High-Value Limits for Parcel and Freight
Comprehensive coverage provides substantial limits designed for commercial operations moving expensive inventory. The platform secures up to $250,000 for parcel shipments and $500,000 for freight shipments, with higher limits available upon review. These thresholds allow companies to consolidate shipments safely without exceeding their protection caps.
Scaling a business requires moving larger volumes of goods and fulfilling higher-value orders. As order values increase, the financial exposure of each individual shipment grows exponentially. Many standard shipping platforms and basic courier insurance options cap their coverage at low thresholds, often maxing out at $1,000 or $5,000. This forces businesses to either break up large orders into multiple smaller shipments (increasing freight costs) or ship the goods with a massive uninsured gap.
ShipSimple addresses this critical bottleneck by providing commercial-grade limits that match the realities of modern B2B and high-end B2C commerce. Whether a business is shipping a pallet of consumer electronics via LTL freight or a single high-value luxury watch via a parcel courier, the platform provides the capacity required to protect the full invoice value. This high-limit capacity is backed by one of North America’s largest commercial underwriters, providing financial stability and reliable payouts.
Parcel Protection for High-Volume E-Commerce
The parcel network is fast, efficient, and inherently chaotic. Couriers like Canada Post, FedEx, UPS, DHL, and Purolator process millions of packages daily. While these networks are highly optimized, the sheer volume dictates that packages will be dropped, crushed, or misdelivered. For e-commerce retailers shipping jewelry, small electronics, or designer fashion, a single lost parcel can erase the profit margin of ten successful sales.
With a $250,000 limit for parcel shipments, businesses can confidently use these fast courier networks for their most valuable items. The coverage attaches from warehouse to warehouse, meaning the goods are protected from the moment they leave the origin premises until final delivery. It is important to note that coverage ends on final delivery. A wrongful or improper delivery (such as a package handed to a fraudster at a fictitious address) does not count as final delivery, and physical loss resulting from such strategic theft remains a covered peril.
Freight and Heavy Machinery Class Conditions
Moving heavy freight requires a different logistical approach and carries distinct risks. Freight carriers and rail operators like CN Rail and CPKC handle massive loads that are susceptible to collision, overturn, and derailment. ShipSimple’s sister company, RailGateway, provides B2B intermodal rail freight across Canada, and securing proper coverage is critical when moving heavy loads on the rail network. The $500,000 freight limit provides the necessary buffer for these large-scale movements.
Different commodities carry different risk profiles, which is reflected in the deductible schedule. For parcel shipments, the deductible is nil. For freight, deductibles vary by class. New or used general merchandise carries a $250 deductible (minimum $2,500 value). Electronics are subject to a deductible of 3 percent of the total insured value, with a minimum of $500. Industrial machinery is covered for freight shipments but is subject to strict class conditions. The deductible for mining, construction, and industrial equipment is 1% the total insured value, minimum $500. Machinery must be containerized, and there is no risk covered while the equipment is under its own power, other than during direct loading and unloading. Used machinery is also subject to a Used Machinery Clause.
Advantage 4: Automated Workflow for Instant Coverage
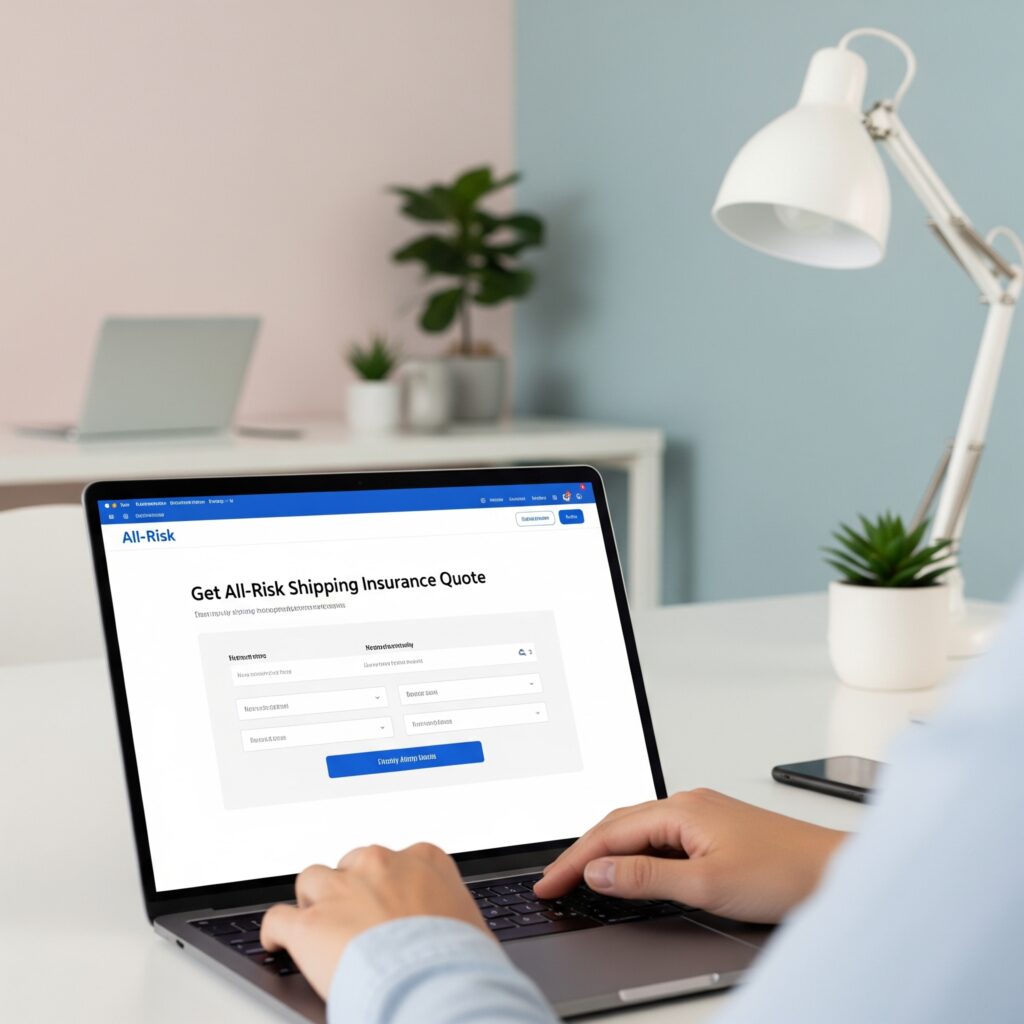
Modern shipping insurance platforms replace manual paperwork with an automated three-step online workflow. Shippers enter product details, shipment details, and address details to bind coverage instantly before the goods leave the warehouse. This digital workflow eliminates administrative delays and means every high-value package is protected prior to transit.
The traditional method of securing cargo insurance was highly manual. Shippers had to contact a broker, fill out PDF applications, wait for a quote, and manually report their shipments at the end of the month. This friction often led to human error, with critical shipments accidentally leaving the dock uninsured because the paperwork was delayed. In a fast-paced logistics environment, any process that slows down fulfillment is a liability.
ShipSimple eliminates this friction entirely. The platform is designed around a seamless, automated workflow that integrates directly into the daily shipping routine. There are no external applications to download. The entire process is handled through a clean, intuitive web interface that allows users to secure top-tier all risk insurance in under a minute.
The Three-Step Digital Workflow
The user experience is built on a straightforward three-step process. First, the user enters the Product Details, including the commodity type and the declared value. Second, they input the Shipment Details, specifying the dimensions, weight, and the chosen carrier. Finally, they provide the Address Details for the origin and destination. Once this data is entered, the system instantly generates a transparent, bindable quote.
This speed is critical for operational efficiency. Warehouse managers do not have time to wait hours for an underwriter to review a standard shipment. By automating the quoting and binding process for approved commodities, the platform empowers businesses to protect their goods at the exact moment of dispatch. Users can bind coverage in under a minute through the three-step web form, meaning that even complex loads can be insured efficiently.
Warehouse to Warehouse Attachment
Understanding exactly when coverage begins and ends is vital for risk management. The policy provides warehouse-to-warehouse protection. This means the coverage attaches the moment the goods leave the origin premises and remains in effect throughout the ordinary course of transit, terminating only upon final delivery at the destination warehouse. This continuous protection includes the critical risk periods of loading and unloading.
It is crucial to recognize the boundary of this service. ShipSimple provides shipping insurance only; it does not move the parcels or freight. The selected carrier moves the physical box, while ShipSimple protects the financial value inside. This clear separation of duties means that the insurance provider remains an objective advocate for the shipper during the claims process, rather than a carrier trying to minimize its own liability.
Advantage 5: Transparent Exclusions and Clear Boundaries
A reliable insurance partner clearly defines what is and is not covered under standard cargo market terms. Perils like mechanical and electrical derangement, rust, and scratching are excluded unless caused by an insured peril. Understanding these boundaries allows shippers to engineer better packaging and manage their transit risks effectively.
No insurance policy covers every conceivable event. Transparency regarding exclusions is what separates a true risk management partner from a platform selling false promises. All-Risk Shipper’s Interest Insurance changes two things: your goods are valued at CIF plus 10 percent instead of the carrier’s weight-based cap, and you collect on proof of physical loss or damage rather than proof of carrier negligence. It does not broaden the list of covered perils beyond standard cargo market terms.
Certain risks are absolutely excluded across the entire cargo insurance market. These absolute exclusions include delay, inherent vice, insufficiency or unsuitability of packing, ordinary wear and tear, ordinary leakage, and the willful misconduct of the insured. Losses caused by nuclear weapons, war, or the insolvency of vessel operators are also strictly excluded. If a shipment of perishable goods spoils because a border inspection caused a three-day delay, that loss is excluded. Delay is an uninsurable risk that must be managed through supply chain planning, not insurance.
Mechanical and Electrical Derangement Realities
One of the most misunderstood areas of cargo insurance involves internal damage to complex goods. Internal electronic or mechanical failure without external evidence of package damage is excluded under ShipSimple’s own policy, unless caused by an insured peril. This is known as the mechanical and electrical derangement (M&ED) exclusion. If a server arrives with a pristine exterior but fails to boot up, that failure is excluded unless caused by an insured peril.
Standard cargo insurance, ShipSimple’s included, shares this exclusion with carriers, meaning it is excluded unless caused by an insured peril. If a CNC machine’s calibration is thrown off by ordinary road vibration, that is not a covered loss. However, if the truck carrying the CNC machine is involved in a collision, or if the crate is dropped from a forklift resulting in visible external damage that subsequently causes internal derangement, the claim is payable. The damage must originate from a covered external transit event.
Insufficient Packing and Inherent Vice
Proper packaging is the shipper’s responsibility and is a fundamental requirement for coverage. Damage resulting from insufficient packing is excluded, ShipSimple’s included. If heavy machinery is loaded into a container without proper blocking and bracing, and it shifts during transit and smashes through the crate, that loss will be denied due to insufficient preparation. Shippers must adhere to industry standards for securing their specific commodities.
Similarly, rust, oxidization, and discolouration (ROD), as well as scratching, denting, marring, and chipping (SDMC), are excluded unless caused by an insured peril. If a vintage guitar develops finish checking due to temperature changes (inherent vice) or minor cosmetic scratches from shifting inside a loose case (insufficient packing), those are not covered losses. However, if the guitar case is crushed by a heavier parcel, resulting in a snapped neck and deep gouges, the physical damage from that external impact is covered.
The Strategic Snapshot: Carrier Liability vs All-Risk Coverage
Comparing standard carrier terms against dedicated insurance reveals stark differences in valuation, claims requirements, and settlement timelines. Standard liability caps payouts by weight and requires the shipper to prove the carrier was at fault. Dedicated coverage responds to physical loss or damage based on the declared value of the goods.
| Feature | Standard Carrier Liability | ShipSimple All-Risk Insurance |
|---|---|---|
| Valuation | Weight-based cap ($4.41/kg) | Invoice product cost, or CIF + 10% recommended, elected when you book |
| What You Need to Claim | Proof the carrier was negligent | Photos and a description of the damage (for freight, plus a repair estimate or third-party confirmation), or tracking showing non-delivery once the carrier’s waiting period has passed, with no need to prove carrier negligence |
| Claim Time | Can take months | Under 30 days for approved submissions |
| Shared Exclusions (M&ED, ROD, SDMC) | Denied | Excluded unless caused by an insured peril |
How to Secure Your Coverage in Three Steps
Securing protection requires a simple digital process that takes less than a minute to complete. Users navigate a streamlined web form to input their commodity details, transit route, and declared value. The system instantly generates a transparent quote that can be bound immediately to protect the outbound shipment.
The transition from relying on inadequate carrier limits to securing comprehensive shipper’s interest protection is entirely frictionless. The platform is engineered to support fast-paced shipping environments where delays are unacceptable. By integrating the quoting and binding process into a simple web interface, businesses can protect their profit margins without slowing down their fulfillment operations.
When a business is ready to ship, they simply log into the platform and follow the three-step workflow. They enter the product details, including the accurate invoice value to help provide proper indemnity. They input the shipment details, selecting their preferred courier or freight carrier. Finally, they confirm the origin and destination addresses. The system instantly calculates the premium based on the declared value and the commodity class, presenting a clear, all-in price. With a single click, the coverage is bound, and the goods are protected from warehouse to warehouse.
Ultimately, choosing to implement a dedicated insurance strategy is about protecting cash flow and preserving customer relationships. When a high-value shipment is destroyed, the financial impact extends far beyond the cost of the goods. It includes lost revenue, wasted freight spend, and the potential loss of a key client. By securing proper coverage, businesses mean they have the financial backing to replace damaged inventory quickly, keeping their supply chain moving and their profit margins secure.
- Get an Instant Shipping Insurance Quote Now
- Learn More About Our All-Risk Damage, Loss, & Theft Coverage
- Contact Our Experts to Secure Your 2026 Shipments
Additional Resources
- Learn More About ShipSimple’s All-Risk Shipping Insurance
- ShipSimple’s Freight & Marine Cargo Shipping Insurance
- ShipSimple’s Parcel Shipping Insurance
- More Helpful Blogs
- Freight Shipping: Master Actual Value Protection, Beyond Standard Carrier Limits
- 7 Costly Mistakes That Kill Profits When Shipping Valuable Goods in Canada
Frequently Asked Questions
What does all risk shipping insurance actually cover?
All risk shipping insurance covers physical loss or damage to goods in transit from external causes, such as collision, overturn, or theft. It values the goods at their declared invoice cost rather than a weight-based carrier limit, subject to standard market exclusions.
How does the claims process work for freight damage?
To process a freight damage claim, the shipper must provide photos of the damaged goods and packaging, a detailed description of the incident, and a repair estimate or third-party confirmation. The claim proceeds without the need to prove carrier negligence.
Are mechanical and electrical failures covered during transit?
Internal electronic or mechanical failure without external evidence of package damage is excluded under standard cargo policies. Mechanical and electrical derangement is excluded unless caused by an insured peril, such as a visible collision or impact during transit.
How is the deductible calculated for industrial machinery?
For freight shipments containing mining, construction, or industrial equipment, the deductible is calculated at 1% the total insured value, minimum $500. The machinery must be containerized to bind coverage.