Key Takeaways
- Section 122 Tariffs permanently increase the landed cost of imported goods, creating a massive financial liability if the cargo is destroyed post-clearance.
- Standard carrier liability is capped at $4.41 per kilogram ($2 per pound) on a standard bill of lading, which completely ignores the cost of non-refundable government duties.
- Understanding Insured Value vs Declared Value is critical, as declaring a value with a carrier only raises their liability ceiling and still requires you to prove carrier negligence.
- To learn how to insure freight duty effectively, shippers must calculate their coverage using the CIF + 10% valuation formula, elected when you book.
- ShipSimple’s automated platform allows shippers to instantly declare their true Total Insurable Value, securing Marine Cargo Insurance that protects the physical goods and the associated tariffs.
Section 122 Tariffs are non-refundable government import surcharges levied at the border that permanently increase the landed cost of your international freight shipments. If your logistics risk model only insures the commercial invoice value of the physical goods, you are absorbing a massive hidden liability gap every single time your freight crosses the border. The ultimate executive answer to mitigating tariff-related cargo exposure lies in proactively structuring your coverage to protect the fully landed cost, definitively including all non-refundable duties.
1. Understanding Section 122 Tariffs and Cargo Valuation
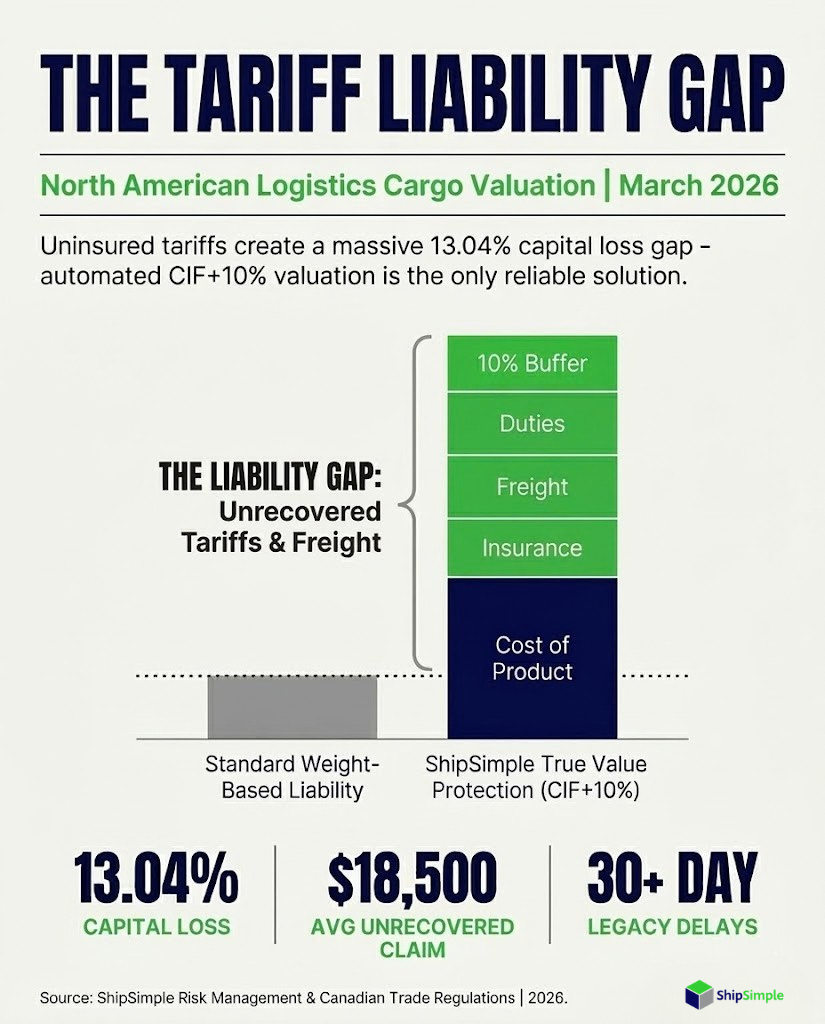
Section 122 Tariffs fundamentally impact cargo valuation by increasing the base landed cost of imported goods, directly exposing a severe capital gap if those items are subsequently lost or destroyed in transit. These non-refundable import surcharges mandate an immediate adjustment in how importers calculate their financial risk.
Why Government Surcharges Impact Your Landed Cost
To truly understand the operational threat, supply chain executives must view government tariffs not just as an operational tax, but as a physical asset risk. According to the Canada Border Services Agency (CBSA), once duties and taxes are assessed and paid upon entry, that capital is permanently decoupled from the physical goods. It is a non-refundable duty. If a heavy commercial shipment transferring from international ocean freight onto CN Rail or CPKC experiences a derailment or catastrophic collision post-clearance, the importer has lost both the physical inventory and the massive tax paid to import it.
Under current trade regulations, standard invoice value policies do not recover non-refundable duties. When Section 122 Tariffs apply, the importer effectively self-insures the government’s tax portion without realizing it. By the time a total loss occurs, the financial damage is already done, and the capital spent on border clearance is entirely irrecoverable.
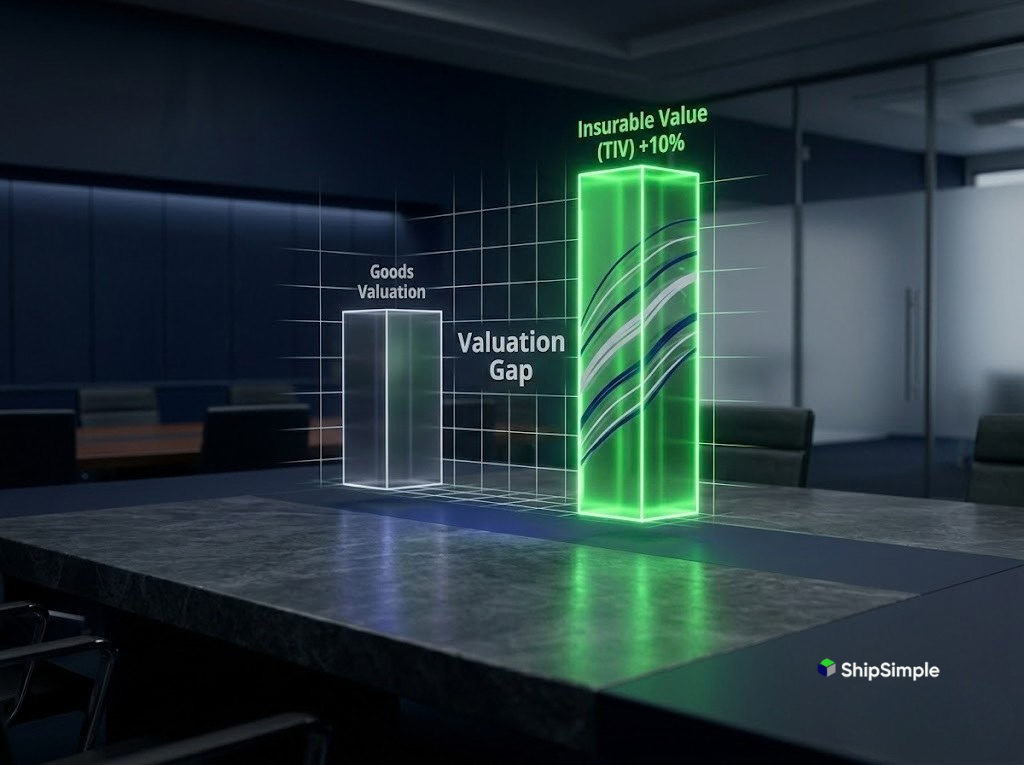
The Danger of the Valuation Gap in Cross-Border Logistics
By failing to account for Section 122 Tariffs within their risk mitigation framework, executives inadvertently place their organizations in a position of high financial vulnerability. Ocean and rail freight liability is strictly limited by weight, completely ignoring ad valorem duty and the true invoice value of the items.
When managing logistics through ShipSimple’s fully automated platform, shippers avoid this vulnerability entirely by instantly declaring proper coverage models that reflect the true landed cost. This proactive approach means that the capital allocated for border clearance is protected alongside the physical asset itself.
Fact Block: The Cost of Uninsured Tariffs
- Standard Carrier Liability: Capped at $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared.
- Duty Non-Refundability: The CBSA rarely issues drawbacks for goods destroyed after they have officially entered the domestic commerce stream.
- ShipSimple Capacity: Up to $250,000 limits for Parcel transit and $500,000 for Freight transit, seamlessly covering high-value exposures.
- Claims Processing Time: Under 30 days for approved submissions, compared to the months it can take to resolve a standard carrier dispute.
2. Insured Value vs Declared Value Under New Trade Regulations
Insured Value vs Declared Value represents the difference between a dedicated underwriter compensating you for your total landed cost and a carrier simply raising their strict legal liability ceiling. Understanding this distinction is paramount for modern logistics executives moving high-value product across international borders.
How Carrier Liability Leaves Duty Unprotected
A declared value is not a legal insurance policy. When you declare a value with a heavy freight carrier or a final-mile courier like FedEx, UPS, DHL, or Purolator, you are simply raising the financial ceiling of their strict legal liability. A standard carrier will never reimburse you for a government-levied tax. If your shipment is destroyed, the carrier assesses the claim based on the physical weight of the goods, leaving the thousands of dollars spent on Section 122 Tariffs completely unprotected.
When evaluating Insured Value vs Declared Value, supply chain leaders must recognize that relying on carrier liability means absorbing the tax burden entirely. A 5,000-pound industrial CNC machine worth $500,000 might incur $75,000 in border surcharges. Under standard carrier terms, a total loss yields a maximum payout of $10,000 based on weight, wiping out both the asset value and the tariff capital.
What You Need to Show in Freight Claims
To successfully execute a claim against a declared value, the shipper must legally prove that the specific carrier was directly negligent. Proving fault is notoriously difficult, especially when dealing with complex multi-modal transit involving third-party interventions. Carriers protect themselves, so the shipper has to go above and beyond to prove the carrier was negligent before a claim is approved, and even then the payout is capped by weight.
Under ShipSimple’s All-Risk Shipper’s Interest Insurance, the debate over Insured Value vs Declared Value is resolved. You collect on proof of physical loss or damage rather than proof of carrier negligence. There is no need to prove carrier fault. The policy pays out based on the value you declared, securing your capital from warehouse to warehouse, door to door, provided the coverage is declared as such and there are no country restrictions.
3. The Uncomfortable Truth About Standard Marine Cargo Insurance
Most standard Marine Cargo Insurance policies are inert to dynamic tariff changes and will only pay out based on the obsolete commercial invoice value listed on a legacy certificate. If your policy was written before the rollout of new border surcharges, you are likely carrying a double-digit liability gap that will only surface during the claims process.
Why Legacy Certificates Fail Dynamic Surcharges
Traditional Marine Cargo Insurance programs are notoriously rigid and require tedious manual updates. They are underwritten based on historical commercial invoice data and rarely account for the sudden implementation of dynamic government surcharges like Section 122 Tariffs. Consequently, when an importer suffers a catastrophic loss, the adjuster calculates the payout strictly based on the outdated sum insured.
By leveraging ShipSimple’s fully automated platform, this static risk is eliminated. As Canada’s fully automated shipping insurance platform, our system allows shippers to dynamically adjust their Total Insurable Value on a per-shipment basis. ShipSimple’s leadership brings over 20 years of deep logistics experience to the table, designing proprietary software to handle dynamic trade realities that traditional brokers simply cannot process fast enough.
Addressing Shared Exclusions in Cargo Policies
It is critical to understand the boundaries of Marine Cargo Insurance. All-Risk Shipper’s Interest Insurance changes two things: your goods are valued at CIF + 10% instead of the carrier’s weight-based cap, and you collect on proof of physical loss or damage rather than proof of carrier negligence. It does not broaden the list of covered perils beyond standard cargo market terms.
If a heavy industrial machine arrives looking fine but will not turn on, this is mechanical and electrical derangement (M&ED). If it arrives with severe surface corrosion, this is rust, oxidization, and discolouration (ROD). These are excluded under standard cargo insurance too, ShipSimple’s included, unless an insured peril caused it. The same applies to scratching, denting, marring, chipping (SDMC), inherent vice, delay, and insufficiency of packing. If your team fails to block and brace the load properly, the resulting damage is excluded across the board.
Strategic Snapshot: Carrier Liability vs ShipSimple
| Feature | Standard Carrier Liability | ShipSimple Automated Insurance |
|---|---|---|
| Valuation | $4.41 per kilogram ($2 per pound) on a standard bill of lading, unless a higher value is declared | Invoice product cost, or CIF + 10% recommended, elected when you book |
| What You Need to Claim | Proof the carrier was negligent | Photos and a description of the damage (for freight, plus a repair estimate or third-party confirmation), or tracking showing non-delivery once the carrier’s waiting period has passed, with no need to prove carrier negligence |
| Claim Time | Can take months | Under 30 days for approved submissions |
| Shared Exclusions (M&ED, ROD, SDMC, Packing) | Denied | Excluded unless caused by an insured peril |
4. How to Insure Freight Duty Effectively Under Ad Valorem Requirements
To effectively learn how to insure freight duty under ad valorem requirements, shippers must calculate their insurance amount based on the comprehensive value of the product using the robust CIF + 10% valuation formula. This explicitly bundles the commercial invoice, transport costs, and all non-refundable duties into one protected sum.
Calculating the True Total Insurable Value (TIV)
Learning exactly how to insure freight duty is the fundamental difference between surviving a total logistics loss and facing a severe capital write-down. Ad valorem taxes inflate the landed cost dramatically. When Section 122 Tariffs trigger, the standard invoice value is no longer an accurate reflection of the asset’s true operational worth.
We confirm that you can explicitly include duties and taxes in the coverage amount under ShipSimple’s All-Risk policy. To avoid the circular mathematical confusion of insurance costs changing the value, the CIF + 10% formula simplifies the process. The insurance amount is calculated directly on the final landed value of the product.
The Role of the CIF + 10% Valuation Formula
Here is the precise executive workflow on how to insure freight duty seamlessly via ShipSimple’s ecosystem:
- Determine the Base Commercial Value: Identify the raw manufacturing cost or purchase price of the goods sold.
- Aggregate Transit Costs: Calculate the total logistics spend, including multi-modal transport.
- Calculate Non-Refundable Duties: Explicitly add the exact cost of the Section 122 Tariffs and any other ad valorem surcharges levied by customs.
- Apply the Valuation Formula: Insure on a CIF + 10% basis, elected when you book. The 10% acts as a critical buffer to cover administrative overhead or unexpected markups incurred during the handling of a severe claim.
- Automate the Declaration: Input this calculated Total Insurable Value into ShipSimple’s fully automated platform to generate instant coverage.
Because ShipSimple provides true All-Risk Shipper’s Interest Insurance, this methodology comprehensively blankets the cargo against physical transit events like drops, crushing, overturn, collision, and derailment.
5. Mitigating Section 122 Risk for High-Value Shippers
ShipSimple mitigates Section 122 Tariffs risk by serving as Canada’s fully automated shipping insurance platform, offering all-risk coverage that directly embeds dynamic valuation parameters into a simple three-step booking process. Through our platform, shippers instantly bundle tariffs into their Total Insurable Value, helping secure capital recovery through CNA-backed underwriting.
Protecting Industrial Machinery and Electronics
With over 20 years of boots-on-the-ground logistics expertise, ShipSimple recognized that businesses shipping high-value goods are highly exposed to Section 122 Tariffs. If a shipment of heavy commercial machinery is insured solely for its manufacturing cost, the tens of thousands of dollars spent on cross-border tariffs vanish if that machinery suffers a catastrophic collision during transit.
Machinery content is covered for Freight, subject to specific class conditions. For the Mining/Construction/Industrial/Mobile/Heavy Equipment and/or Machinery class, the deductible is 1% of the total insured value, minimum $500. There is no risk covered while the equipment is under its own power, other than during direct loading and unloading, and used equipment is subject to a Used Machinery Clause. By understanding these parameters, shippers can confidently secure their heavy assets.
Understanding Real-World Liability Limits
Real-world Marine Cargo Insurance liability limits vary strictly by the underwriter’s established parameters and the specific Total Insurable Value declared by the shipper. Unlike generic carrier limits, comprehensive policies explicitly define maximum sums insured based on a fully aggregated landed cost valuation.
The absolute danger of relying on standard courier liability limits or ocean freight tariffs cannot be overstated. When moving high-value product, understanding the deep nuances of Insured Value vs Declared Value is your best defense against catastrophic loss. Standard couriers and ocean lines alike will leverage every available legal defense to avoid paying a claim, frequently citing inherent vice or insufficiency of packing.
With ShipSimple, the real-world limits are robust and clearly defined. We secure massive, high-limit approvals of $250,000 for Parcel shipments moving via couriers and $500,000 for Heavy Freight for permitted commercial goods. Higher limits are available on a per-customer basis upon review.
6. Strategic Steps to Ensure Full Compliance and Coverage
Importers must strategically audit their current logistics contracts to ensure that their risk models explicitly account for ad valorem taxes and dynamic border surcharges. Shifting away from generic carrier limits to an automated, all-risk marine policy helps secure comprehensive financial protection for your entire landed cost.
Integrating Tariff Tracking into Your Logistics Model
To truly secure your logistics chain against the severe threat of Section 122 Tariffs, supply chain leaders must adopt a highly protective approach to cargo valuation. Review the fine print with your ocean freight lines and parcel couriers. Confirm the reality of Insured Value vs Declared Value within your current setup. If you are relying on standard declared value, you are definitively uninsured for duty recovery.
Mandate that your logistics team dynamically updates the Total Insurable Value for every international shipment to explicitly include Section 122 Tariffs. Always use the Cost, Insurance, and Freight + 10% model. Calculate the insurance amount directly on the full landed value of the product.
If your supply chain involves complex rail moves, ShipSimple’s sister company, RailGateway, provides B2B intermodal rail freight across Canada, while ShipSimple protects the value of the cargo inside the container.
Moving to an Automated Insurance Portal
Move away from manual broker certificates. Implement ShipSimple’s fully automated platform to instantly generate CNA-backed coverage, ensuring there is zero lag time between freight booking and coverage inception. The workflow is a simple three-step process: Product Details, Shipment Details, and Address Details.
Familiarize yourself with standard exclusions. Ensure your teams are packing high-value goods correctly to prevent insurers from challenging claims based on unsuitability of preparation. Remember that settlement is based on indemnity; a damaged shipment is assessed and settles as either the cost to repair or, where repair is uneconomic against the sum insured, as a total loss at the declared value.
By implementing these technical steps and mastering how to insure freight duty, your organization effectively transforms a massive financial vulnerability into a highly controlled operational standard. Marine Cargo Insurance is no longer just a static safety net; through ShipSimple, it is a dynamic, automated asset protection tool.
Secure Your Landed Costs Today
Don’t let government surcharges create a massive liability gap in your supply chain. Ensure every dollar of your Total Insurable Value is protected with ShipSimple, Canada’s fully automated shipping insurance platform.
- Get an Instant Shipping Insurance Quote Now
- Learn More About Our All-Risk Damage, Loss, & Theft Coverage
- Contact Our Experts to Secure Your 2026 Shipments
Additional Resources
- Learn More About ShipSimple’s All-Risk Shipping Insurance
- ShipSimple’s Freight & Marine Cargo Shipping Insurance
- ShipSimple’s Parcel Shipping Insurance
- More Helpful Blogs
Frequently Asked Questions
What are Section 122 Tariffs and how do they affect shipping insurance?
Section 122 Tariffs are non-refundable government surcharges levied on imported goods that significantly inflate the true landed cost of a shipment. If these exact tariffs are not explicitly included in the Total Insurable Value of a cargo insurance policy, the shipper will suffer a massive, unrecoverable capital loss if the goods are destroyed in transit.
How does Insured Value vs Declared Value impact claim payouts?
Insured Value vs Declared Value dictates how you recover losses. Insured value allows you to claim against a declared sum backed by an underwriter without proving carrier fault. Declared value simply raises a standard carrier’s legal liability limit, requiring the shipper to definitively prove carrier negligence to receive any compensation.
What is the best method for how to insure freight duty on high-value cargo?
The most effective method for how to insure freight duty is to use a CIF + 10% valuation model through a platform like ShipSimple. By calculating the insurance amount on the total landed value of the product, including non-refundable duties, you help secure complete recovery of all ad valorem taxes in the event of a covered total loss.
Does standard Marine Cargo Insurance cover Section 122 Tariffs automatically?
No, standard Marine Cargo Insurance policies insure only the commercial invoice value unless specifically instructed otherwise. Shippers must proactively and explicitly declare a Total Insurable Value that bundles these tariffs to avoid a massive valuation gap.
How fast is the claims process with ShipSimple compared to standard carriers?
Standard freight carrier claims routinely take months and require exhausting proof of fault. ShipSimple’s fully automated platform allows instant digital submission with required documentation, resolving approved claims in under 30 days with no need to prove carrier negligence.